
Equipment / Inland Marine Insurance
Coverage for Business Property That Doesn’t Always Stay Put
Many businesses depend on tools and equipment that travel wherever the work takes them. John Scott Insurance helps you protect mobile property, equipment and materials with Inland Marine Insurance.
What Is Inland Marine Insurance?
Inland Marine Insurance is a category of insurance designed to cover certain types of property that:
- Move from one location to another
- Are transported in vehicles or trailers
- Are used at job sites
- Are temporarily stored away from the primary business location
- Require specialized property coverage
- May not fit neatly within a standard Commercial Property policy
The exact coverage depends on the policy, property and business operation.
The name Inland Marine Insurance remained.
Today, businesses commonly use Inland Marine coverage for tools, equipment and other eligible property that moves away from a fixed business location.
Why is it called “Inland Marine”?
This is one of the most common questions about this coverage.
Historically, marine insurance developed to protect goods being transported over water.
As commerce expanded inland, insurance coverage evolved to protect certain property while it was being transported over land or moved between locations.
What Can Inland Marine Insurance Cover?
Coverage varies significantly depending on the type of property and insurance policy. Depending on the business and policy, coverage may be available for certain property such as:
Contractor tools
Construction equipment
Portable Equipment
Machinery
Property transported between locations
Specialized equipment
Property temporarily located at job sites
Certain materials awaiting installation
Other eligible mobile business property
Tools and Equipment in Work Trucks
Are the tools in my work truck covered by Commercial Auto Insurance?
Not necessarily. Commercial Auto Insurance is primarily designed to address the vehicle and auto-related exposures.
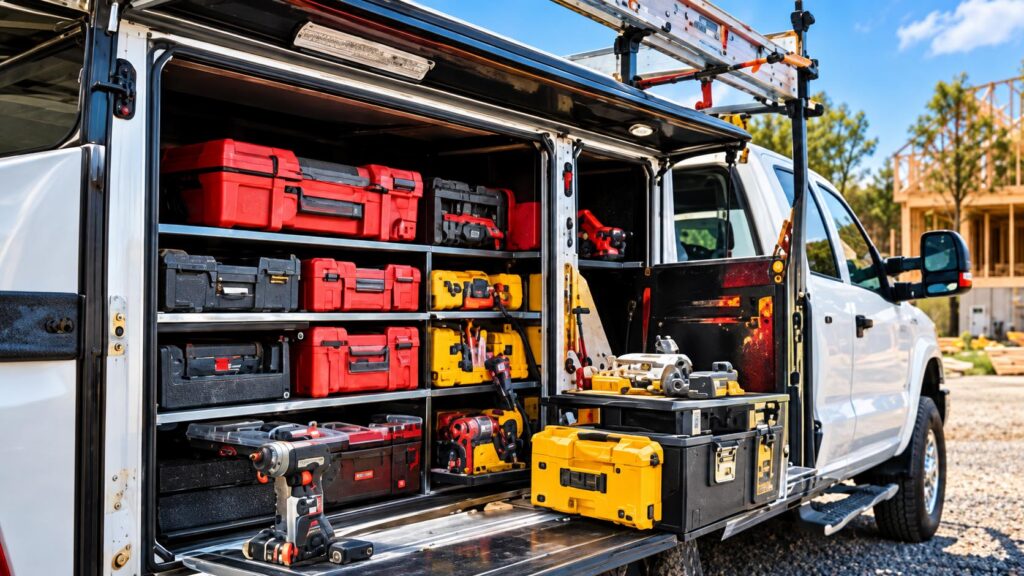
The tools, equipment and machinery being transported in or on the vehicle may require separate property coverage. Depending on the business and equipment, Inland Marine Insurance may be used to help protect those items
Does Inland Marine Cover Theft?
Depending on the policy and circumstances, it may provide coverage for certain theft losses involving insured tools or equipment. Coverage can depend on:
Where the property was located
How it was stored
Whether there was evidence of theft
Policy exclusions, limits and deductibles
Other policy requirements
Understand how your policy treats tools left overnight in vehicles, trailers or job sites.
How Much Equipment Coverage Do I Need?
Consider the current value of everything your business depends on:
Large machinery & specialized equipment
Hand tools and power tools
Computers or electronics used in the field
Equipment stored in vehicles and trailers
Newly purchased equipment
Rented or borrowed equipment, where applicable
It’s easy to underestimate how much you have invested in tools. A truck or trailer filled with equipment can represent a significant amount of money. Regular inventories help keep limits current.
Scheduled Equipment
Higher-value equipment may be specifically listed on the policy with:
- Description, make & model
- Serial number
- Value
Keep These Equipment Records
-
Description, make and model
-
Serial number
-
Purchase date & price
-
Current value
-
Photos & receipts
-
Location
-
Owned, leased or rented
Accurate records help with insurance reviews and following a loss.
Unscheduled Equipment
Certain lower-value tools and equipment may be covered under a blanket or unscheduled limit, depending on the policy. Keep accurate records so insurance reflects what you actually own.
Rented or Borrowed Equipment
Contractors and other businesses may occasionally rent, lease or borrow equipment. Coverage depends on the policy and rental agreement. Discuss these arrangements with your insurance professional before assuming rented equipment is automatically covered — rental companies may also have specific insurance requirements.
Equipment stored securely at one location is a very different exposure than equipment traveling to multiple job sites every day.
What Affects the Cost?
We’ll help you understand your property exposures, review your current coverage and make sure your business is protected from the unexpected.
✓ Type of equipment
✓ Equipment value
✓ Number of items
✓ Business operations
✓ Where used & stored
✓ How transported
✓ Theft exposure
✓ Claims history
✓ Limits & deductibles
✓ Operating area
✓ Security practices
Exactly what’s covered depends on the policy, limits, valuation method, exclusions and circumstances of the loss.
Equipment Insurance for Contractors
Thousands of dollars — or significantly more — in tools and equipment. Exposures include equipment theft, job-site losses, tools in vehicles and trailers, equipment moved between jobs, rented and borrowed equipment, newly purchased items and specialized machinery.
Equipment Insurance for Tree Service
Chippers, stump grinders, chainsaws, climbing and rigging equipment, portable tools and specialized machinery — often at multiple job sites every day. Understand how equipment is insured in transit, at job sites and overnight.
Frequently Asked Questions About Inland Marine Insurance
Why is it called Inland Marine Insurance?
The term developed historically from marine insurance used for goods in transit. Today it commonly protects certain property that moves over land or away from a fixed business location.
What does Inland Marine Insurance cover?
Depending on the policy, certain tools, equipment, machinery, materials and other eligible property that travels or is used away from the primary location.
Does Commercial Auto Insurance cover tools in my truck?
Not necessarily. Commercial Auto primarily addresses the vehicle and auto-related exposures. Tools and equipment may require separate Equipment or Inland Marine coverage.
Does Inland Marine cover stolen tools?
Certain theft losses may be covered depending on the policy and circumstances. Review theft limitations, exclusions, deductibles and storage requirements.
Can Inland Marine cover equipment at a job site?
Certain equipment used or temporarily stored at job sites may be eligible, depending on the policy.
Can I insure rented equipment?
Coverage may be available for certain rented or leased equipment, but review your policy and rental agreements.
Do I need to list every piece of equipment?
Some higher-value equipment may need to be individually scheduled, while lower-value items may qualify for blanket or unscheduled coverage. This varies by policy.
How do I know how much equipment insurance I need?
Maintain a current inventory of tools and equipment and consider what it would cost to replace those items following a covered loss.
Does Inland Marine cover equipment in multiple states?
Coverage territory depends on the policy. Businesses that transport equipment across state lines should discuss their full operating area with their insurance professional.
Part of Your Business Insurance Program
Protecting the equipment itself is only one part of the picture. Depending on the business, additional coverage may include:
Explore Business InsuranceEquipment Insurance Across the Midwest
John Scott Insurance works with commercial clients throughout:
Michigan | Indiana | Illinois | Wisconsin | Iowa | Minnesota
Businesses operating in multiple states should discuss their full operations and contractual requirements with their insurance professional.
Protect the Equipment That Keeps Your Business Working
For many businesses, losing a truckload of tools or an essential piece of equipment doesn’t just create a property loss. It can bring work to a stop.
We can help you identify the tools and equipment your business depends on, review how they’re currently insured and determine whether Equipment / Inland Marine coverage belongs in your overall program.